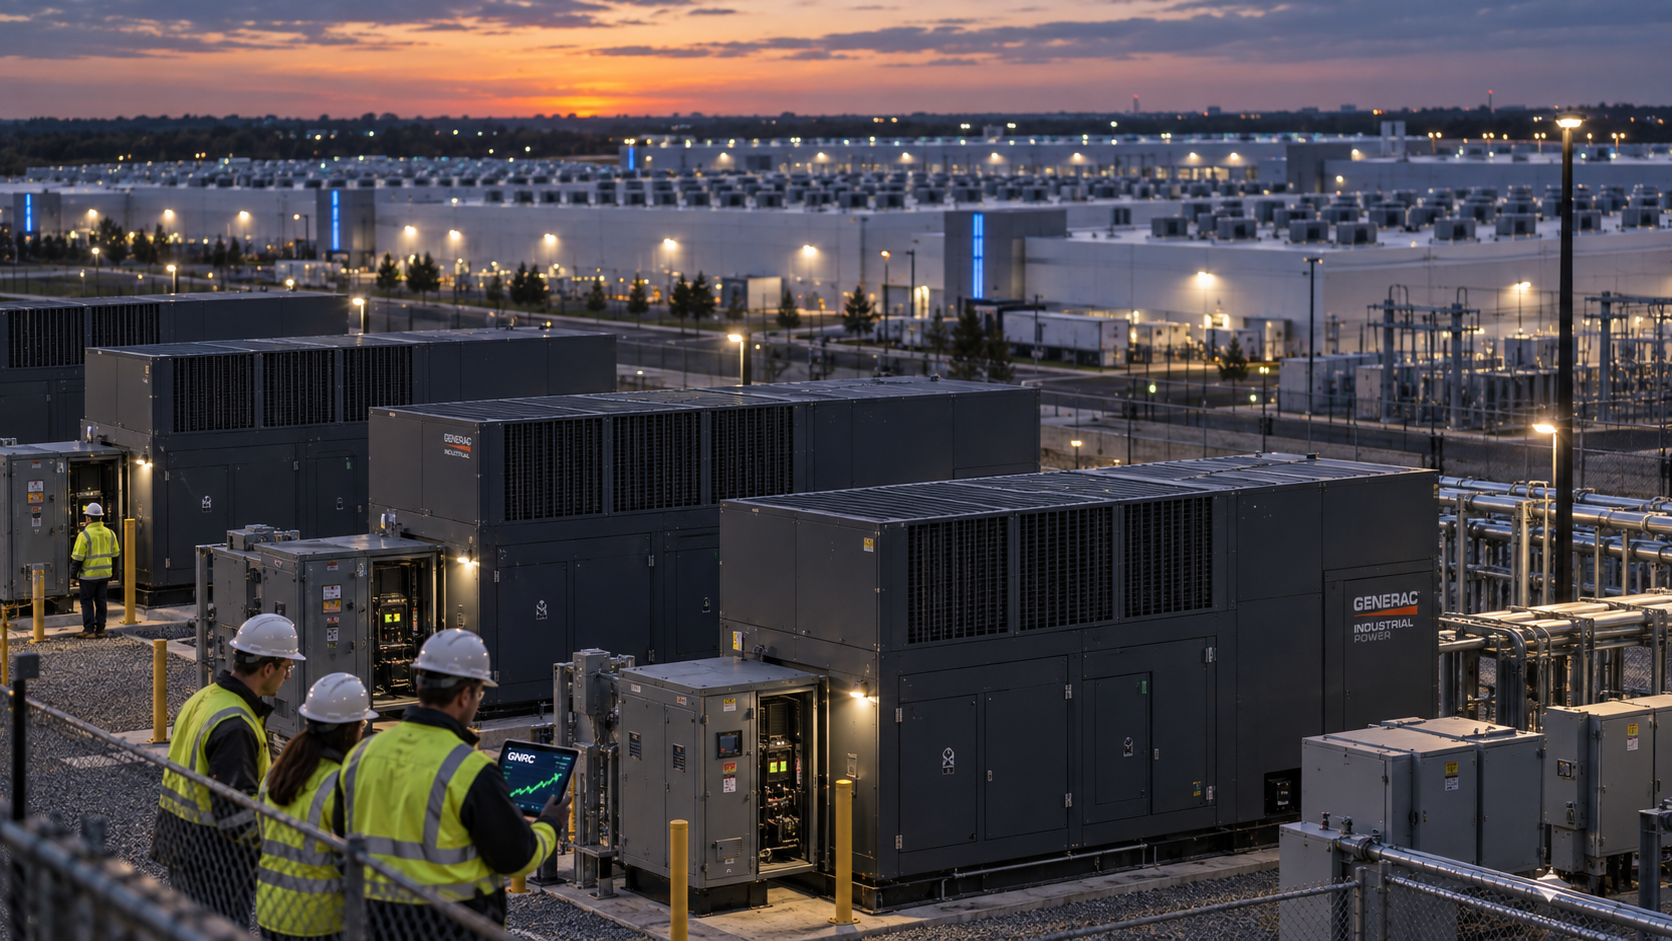
Generac stock (NYSE: GNRC) surged about 34% in premarket trading on Thursday after Amazon committed billions of dollars to backup generators for its expanding data-centre network, but the agreement gives Amazon more than equipment.
Generac expects initial deliveries worth $2.4 billion across 2027 and 2028, while payments tied to the broader relationship could reach $8 billion.
In return, Amazon received warrants allowing it to buy as many as 1.69 million Generac shares at about $201 each.
That creates an unusual trade-off for shareholders, as the larger the commercial relationship becomes, the larger Amazon’s potential equity stake in Generac.
Amazon transforms Generac’s data-centre growth story
The scale of the agreement explains the market reaction.
Generac generated $4.21 billion of total revenue in all of 2025. Against that base, $2.4 billion of planned Amazon deliveries across only 2027 and 2028 is substantial.
The company was already building momentum in data centres. Its backlog had reached about $1.6 billion by late July, while second-quarter commercial and industrial sales rose 29% to $556 million, driven partly by growing data-centre revenue.
Cantor Fitzgerald called the Amazon agreement Generac’s “most important data centre” development since its first hyperscaler win, according to TipRanks.
The firm maintained an Overweight rating and $333 target, arguing that the deal addresses questions about replenishing Generac’s backlog beyond 2027.
That is the real significance. Amazon turns a promising expansion business into one with far greater revenue visibility and gives Generac a marquee customer at the centre of the AI infrastructure boom.
The catch is Amazon gets more equity as it spends more
The unusual part of the agreement sits in the warrant, as Amazon can acquire up to 1,693,745 Generac shares at an exercise price of $200.9266.
A total of 307,954 shares vested immediately, while the remainder vest in multiple stages as qualifying payments from Amazon rise towards $8 billion.
If fully vested and exercised, the warrant would represent nearly 3% of Generac’s outstanding shares.
That is potential dilution, but it is not simply Generac giving away equity. The structure links Amazon’s ownership upside directly to the amount of business it sends Generac.
Baird had already upgraded Generac to Outperform this month, calling the setup an “attractive risk reward” and pointing to large commercial and industrial generators as an important new growth opportunity.
The Amazon agreement now provides concrete evidence behind that thesis.
The bargain seems clear for shareholders as Amazon gains equity exposure if the partnership becomes much larger, while Generac gains billions of dollars of potential orders and stronger factory utilisation.
Amazon success could create a different risk
The deal also changes what investors need to worry about.
Jefferies earlier this year described Generac’s hyperscaler push as a “moment of truth” as the company tried to prove that its larger generators could win serious data-centre contracts.
Amazon suggests Generac has passed that test.
But success brings customer-concentration and execution risk. A larger share of future growth would depend on hyperscaler capital spending, Amazon’s purchasing schedule, Generac’s ability to deliver large generator programmes and continued data-centre construction.
The warrant reinforces that relationship because Amazon’s potential ownership rises alongside its commercial importance.
That concentration could eventually matter as much as the headline revenue.
Generac shareholders are therefore exchanging some potential future dilution for visibility into billions of dollars of hyperscaler spending.
Whether the rally proves justified will depend on how quickly those orders translate into earnings and whether Generac can use Amazon as a launchpad to win additional data-centre customers.